Marketplace Open Enrollment
Through the Affordable Care Act, the Health Insurance Marketplace® (Marketplace) open enrollment is a period of time each year when you can sign up for health insurance or change your plan.
To learn more about your options, see below:
- Open Enrollment
- How to Pick the Best Plan for You
- Health Insurance Requirement
- What to Do if You Cannot Afford Health Insurance
- Special Enrollment Period
Open Enrollment
Marketplace open enrollment for health coverage is a period each year when individuals who are not eligible for Medicare or Medicaid and don't have employer-sponsored health insurance can sign up for a health plan or make changes to the health plan they’re already enrolled in. This is completed through the Health Insurance Marketplace® or “exchange.” Individuals may also browse or contact the Marketplace to determine eligibility for a Marketplace plan if their employer’s coverage is not affordable.
An employer-sponsored health plan is considered “affordable” if an employee’s required contribution for the employer’s lowest-cost, self-only plan that provides minimum value is not more than a certain percentage of their household income.
For 2026, the affordability threshold is 9.96%. For 2027, the affordability threshold is 10.22%
This year, the Marketplace open enrollment period runs from November 1, 2026, to January 15, 2027 (for most states). States with their own individual marketplace and deadlines are listed below.
Note: If you enroll by December 15, 2026, your coverage can start January 1, 2027; if you enroll between December 16 and January 15, coverage will start February 1, 2027.
| State | Deadline | Website |
|---|---|---|
| California | January 31 | www.coveredca.com |
| Colorado | January 15 | connectforhealthco.com |
| Connecticut | January 15 | www.accesshealthct.com |
| District of Columbia | January 31 | www.dchealthlink.com |
| Georgia | January 15 | georgiaaccess.gov |
| Idaho | December 15 | www.yourhealthidaho.org |
| Illinois | January 15 | getcovered.illinois.gov |
| Kentucky | January 15 | kynect.ky.gov |
| Maine | January 15 | www.coverme.gov |
| Maryland | January 15 | www.marylandhealthconnection.gov |
| Massachusetts | January 23 | www.mahealthconnector.org |
| Minnesota | January 15 | www.mnsure.org |
| Nevada | January 15 | www.nevadahealthlink.com |
| New Jersey | January 31 | www.nj.gov/getcoverednj |
| New Mexico | January 15 | bewellnm.com |
| New York | January 31 | www.nystateofhealth.ny.gov |
| Pennsylvania | January 15 | www.pennie.com |
| Rhode Island | January 31 | www.healthsourceri.com |
| Vermont | December 28 | https://portal.healthconnect.vermont.gov |
| Virginia | January 29 | www.marketplace.virginia.gov |
| Washington State | January 15 | www.wahealthplanfinder.org |
Apply on healthcare.gov for all other states.
How to Pick the Best Plan For You
There are many factors to consider when selecting health insurance.
1. Decide how you will obtain health insurance
There are a few options for getting health coverage:
- Your employer.
- Federal marketplace or exchange (healthcare.gov).
- Your specific state’s marketplace or exchange.
- A private exchange or directly from a private insurer.
The Affordable Care Act requires that health plan providers include these Essential Health Benefits as part of their plans.
2. Determine which type of plan is best for you
After deciding how you will obtain health insurance, determine which type of plan is the best fit for you. There are three main types of health plans- Health Maintenance Organization (HMO), Exclusive Provider Organization (EPO), and Preferred Provider Organization (PPO). Each have different benefits. To compare these different plan types, consider the factors outlined in the chart below. Ask yourself which of these factors is most important to you, then use the chart to determine which plan best fits your needs.
HMO
Health Maintenance OrganizationEPO
Exclusive Provider OrganizationPPO
Preferred Provider OrganizationDoes the plan require you to select a designated Primary Care Physician? Yes Sometimes No Does the plan require a referral to see a specialist if you want or need to? Yes No No Does the plan cover health expenses from doctors, hospitals, or providers within the Provider Directory? Yes Yes Yes Does the plan cover health expenses from doctors, hospitals, or providers outside of the plan’s network? No No Yes How expensive will your monthly payments be? $ $$ $$$$ Can you use a Health Savings Account to set aside pre-tax money to pay for costs not covered by your plan? Only if the plan is an HSA-qualified High Deductible Health Plan Does the plan have very high out-of-pocket costs for health expenses but very low regular monthly payments? Sometimes Sometimes No
3. Compare plans
Plans are presented into four tiers: bronze, silver, gold & platinum. Consider the following factors when deciding what type of plan to select:
- The benefits covered
- The "provider directory" which features the clinics and doctors that participate in the plan’s network
- Cost
See below to determine which tier is right for you:
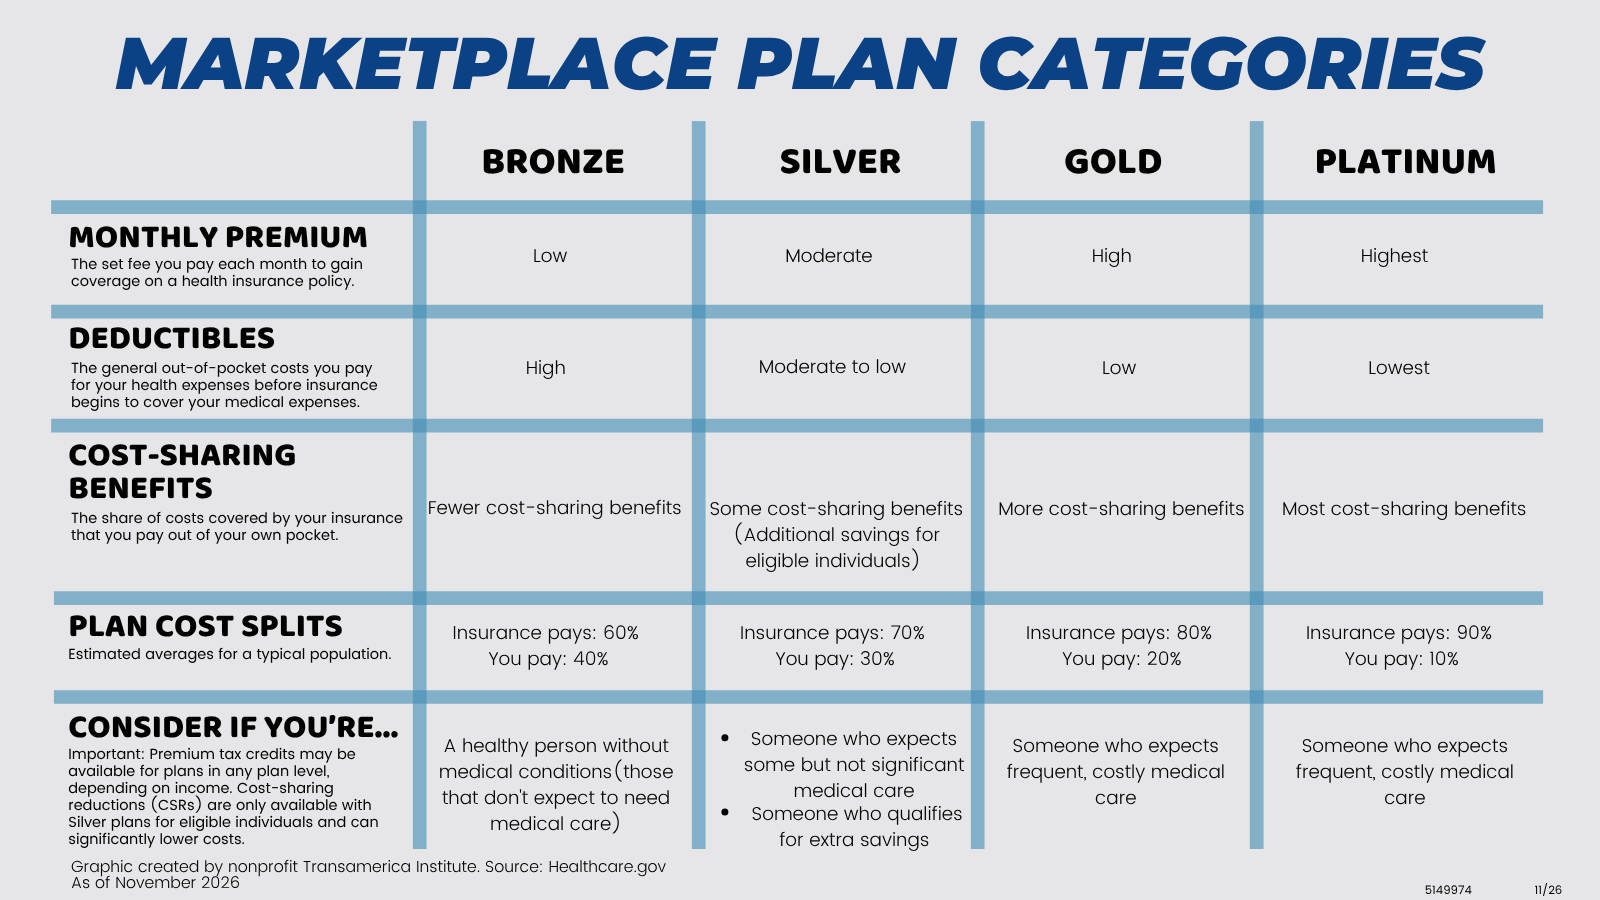
Note: Individuals may be eligible for a Silver plan with "extra savings" if they meet certain requirements. Learn about cost-sharing reductions at healthcare.gov.
In the Marketplace, cost-sharing reductions are often called “extra savings.” Extra savings are discounts that lower the amount you pay for deductibles, copayments, coinsurance, and out-of-pocket maximums. When you fill out a Marketplace application, you’ll find out if you qualify for premium tax credits and extra savings. If you qualify, you must enroll in a Silver plan to get the extra savings. Cost-sharing reductions apply only to Silver plans.
4. Determine your monthly cost
Premiums are the monthly costs you pay for your health insurance, and deductibles are the out-of-pocket costs you must pay for your health expenses before insurance begins to cover your medical expenses. Typically, paying higher monthly premiums allows for lower deductibles, and paying lower monthly premiums allows for higher deductibles.
To decide if you want a high premium/low deductible plan or a low premium/high deductible plan, consider how often you will be using health services. A plan with a higher premium that covers a higher portion of your medical costs may be appropriate if:
- You see a primary physician or a specialist frequently
- You take expensive medications on a regular basis
- You are expecting a baby or plan to have a baby
- You have a surgery coming up
- You need emergency care frequently. You’ve been diagnosed with a chronic condition
Options for Managing Out-of-Pocket Costs
If you are considering a High Deductible Health Plan (HDHP), which may have lower monthly premiums but higher deductibles and out-of-pocket costs, determine what options the plan allows for managing the out-of-pocket costs you may incur. Some HDHPs allow you to use the following alternative sources to help pay for your out-of-pocket payments.
- Health Savings Account (HSA): a type of savings account that allows you to set aside pre-tax money to pay for certain eligible medical expenses.
- Health Reimbursement Arrangement (HRA): an arrangement that reimburses employees tax-free for certain eligible medical expenses, funded by their employer.
Health Insurance Requirement
Federal law no longer requires individuals to purchase health insurance; however, the following states have a mandate (which may have a penalty):
- California
- District of Columbia
- Massachusetts
- New Jersey
- Rhode Island
- Vermont (No penalty if uninsured)
What to Do if You Cannot Afford Health Insurance
For people who cannot afford traditional health insurance, the following options are available. Please note that if you are concerned about your ability to afford health insurance, it is best to seek advice and assistance from a professional. Many states have Navigators who can answer your questions and walk you through this process. The "Find Local Help" link on healthcare.gov or your state’s Marketplace website can connect you with one of these individuals.
Medicaid and Children’s Health Insurance Program (CHIP)
If you have a low income, you may qualify for health coverage through a state agency. Medicaid provides free or low-cost coverage to eligible low-income adults, families and kids, pregnant women, older adults, and people with disabilities. The Children’s Health Insurance Program (CHIP) provides low-cost coverage to children in families that earn too much to qualify for Medicaid. You can apply for Medicaid or CHIP at any time through either the Health Insurance Marketplace or your state’s Medicaid agency.
Catastrophic Coverage
Catastrophic health plans are a low-cost option you can buy through the Health Insurance Marketplace. They have relatively low monthly premiums but very high deductibles. To meet eligibility requirements for catastrophic coverage, you must be under 30 years old or qualify for a hardship exemption or affordability exemption due to your inability to afford all other insurance options. These plans cover the same ten essential health benefits as other Marketplace plans and three primary care visits per year before you meet your deductible. Note: Catastrophic plans are not eligible for premium subsidies.
Short-Term Health Insurance
Short-term health insurance is available outside the marketplace, and you do not have to meet income standards to qualify. These plans have low monthly premiums; however, they are set for a designated period and offer limited benefits. These plans are not Qualifying Health Coverage and do not meet Affordable Care Act requirements.
Supplemental Products
Supplemental products are a type of insurance used to pay for costs not covered by your primary health coverage. As an add-on, these specific insurance products are used to cover out-of-pocket expenses and even help with everyday expenses, and in some cases, may be paid directly to you. Some people might even use supplemental products on their own if they cannot afford health insurance. However, it can be difficult to calculate the benefit paid under the policy and anticipate any exclusions. Examples of supplementary products are insurance plans specifically for dental, vision, accidents, fixed indemnity, cancer, hospitalization, critical illness, or travel.
Advance Premium Tax Credit
If you are struggling to afford traditional health insurance, an Advance Premium Tax Credit (APTC) can help you lower your monthly health insurance premiums. When you apply for coverage through the Health Insurance Marketplace, you provide an estimated income for the year. If this estimate allows you to qualify for a premium tax credit, you can use any amount of it in advance to lower your premium payments.
Note: The temporary enhanced premium tax credits that were available from 2021 through 2025 have expired. Standard ACA premium tax credit rules still apply.
Special Enrollment Period
Certain life events, such as losing health coverage, getting married, having a baby, moving, or having a household income below a certain amount, may qualify you to enroll in or change Marketplace health plans outside of the annual Open Enrollment Period, which starts November 1.
For most Special Enrollment Periods, people with existing Marketplace coverage and their dependents (including newly added household members) may be limited to selecting a plan within their current plan category. For example, if you're already enrolled in a Bronze health plan and want to change plans, you may only be able to select another Bronze plan. However, certain qualifying events allow you to change plan categories.
Note: For 2026, the year-round Special Enrollment Period based solely on low income is no longer available through HealthCare.gov.
Changes in Household
If any of these happened to you or someone in your household in the last 60 days, you may qualify for a Special Enrollment Period:
- Got married
- Had a baby, adopted, or placed a foster child
- Lost health coverage when you got divorced or legally separated
- If someone on your health plan dies and you lose eligibility with your current plan
Changes in Residence
Changes in residence that may qualify you for a Special Enrollment Period:
- Moving to a different ZIP code or county
- Moving to the US from another country or territory
- Moving to and from the place you attend school (if you're a student)
- Moving to or from the place you work (if you're a seasonal worker)
- Moving to or from transitional housing or a shelter
- Moving only for medical treatment or staying somewhere for vacation doesn’t qualify you for a Special Enrollment Period.
You must prove you had qualifying health coverage for one or more days during the 60 days before your move. You don't need to provide proof if you’re moving from a foreign country or a United States territory.
Loss of Health Insurance
You may qualify for a Special Enrollment Period if you or anyone in your household lost qualifying health coverage in the past 60 days OR expects to lose coverage in the next 60 days.
- Coverage Losses that may qualify you for a Special Enrollment Period:
- Losing job-based coverage
- Losing individual health coverage
- Losing eligibility for Medicare
- Losing eligibility for CHIP or Medicaid
- Losing coverage through family
Situations That Allow You to Change Plan Categories
Individuals in these circumstances may qualify for a Special Enrollment Period to change plan categories (for example, from Bronze to Silver) in certain circumstances between 60 days before and 60 days after certain situations such as:
- Becoming eligible for extra savings ("cost-sharing reductions")
- Losing eligibility for extra savings in a Silver plan
- New household members
- If you can’t add new household members to your plan
- An employer offers to help with the cost of coverage
An Employer Offers to Help With the Cost of Coverage
You may qualify for a Special Enrollment Period if you or anyone in your household gained access to an Individual Coverage Health Reimbursement Arrangement (HRA) or a Qualified Small Employer Health Reimbursement Arrangement (QSEHRA) in the last 60 days or expects to in the next 60 days.
Other Qualifying Changes
- Gaining membership in a federally recognized tribe or status as an Alaska Native Claims Settlement Act (ANCSA) Corporation shareholder
- Becoming a US citizen
- Leaving incarceration
- Starting or ending service as an AmeriCorps State and National, VISTA, or NCCC member
- Being affected by an unexpected and uncontrollable event or natural disaster (like an earthquake, massive flooding, or a hurricane)
Last updated: November 2, 2026
11/25 5030264